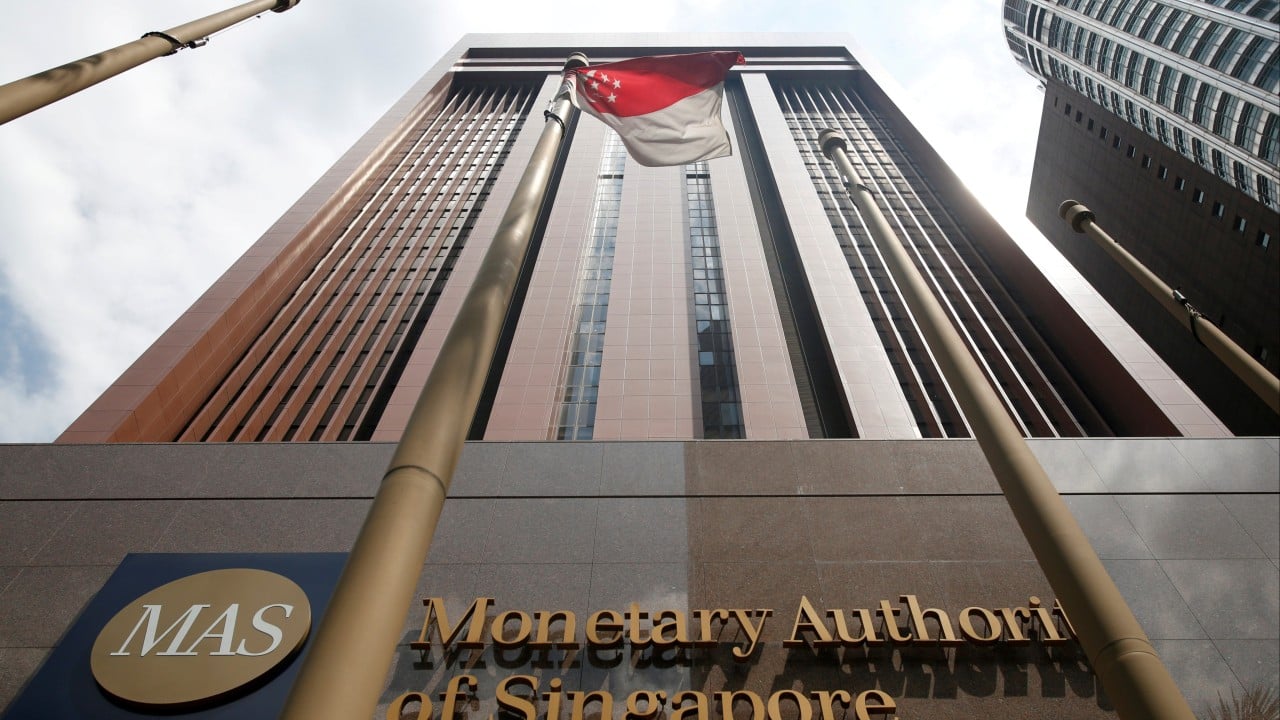
Singapore isn't playing around anymore when it comes to the battle for financial supremacy in Asia. The Monetary Authority of Singapore just pumped another S$1.45 billion—about US$1.1 billion—into five global asset managers. This move marks the third wave of funding under the massive S$6.5 billion Equity Market Development Programme, bringing total allocations to a staggering S$5.4 billion.
If you've been watching the perennial tug-of-war between the Lion City and Hong Kong, you know this capital injection is part of an aggressive strategy to breathe life back into local equities. For years, critics pointed out that Singapore's stock market suffered from sleepy trading volumes and a lack of blockbuster initial public offerings. Officials are now tackling that head-on by injecting serious state backing into the hands of giants like Amundi, Franklin Templeton, HSBC Asset Management, M&G Investments, and Natixis Investment Managers.
The Strategy Behind the S$1.45 Billion Injection
Throwing money at institutional asset managers sounds simple, but the mechanics matter. The goal here isn't just to park cash in local counters. Singapore wants these heavyweights to actively commit to building up regional investment strategies with a permanent anchor in local markets.
Alongside the manager selection, authorities introduced a S$20 million grant aimed specifically at market-making for small- and mid-cap stocks, plus fresh incentives for new listings. For too long, smaller companies on the Singapore Exchange struggled with chronic liquidity shortages. When nobody trades your shares, valuations slump, and founders look elsewhere to go public. By incentivizing market makers to narrow spreads and keep order books active, regulators are trying to fix the plumbing of the exchange.
Can Singapore Really Outpace Hong Kong?
Hong Kong has historically worn the crown for sheer IPO size and capital raising velocity, heavily fueled by its status as the primary gateway to mainland China. That unique pipeline gave Hong Kong an unbeatable edge during peak bull markets.
Yet, geopolitics changed the playbook. Shifting global supply chains and regulatory realignments forced multinational corporations and family offices to rethink where they park their capital. Singapore capitalized on this by scooping up wealth management business, but its public equity markets lagged behind the private wealth boom.
This S$6.5 billion push is the missing puzzle piece. Singapore is betting that if you can't rely purely on a massive domestic corporate pipeline like Hong Kong's, you can engineer market depth by seeding professional asset managers with state-backed capital and rewarding primary listings with tax rebates.
What This Means for Investors and Founders
If you run a high-growth company trying to decide where to list, or if you manage a regional portfolio, these structural shifts demand attention. Singapore is lowering the friction for primary listings and throwing regulatory weight behind small- and mid-cap liquidity.
At the same time, the competition forces Hong Kong to sweeten its own offerings to retain dominant tech and finance listings. The real winner of this rivalry is the broader Asian financial ecosystem, which benefits from two major hubs racing to offer better terms, deeper liquidity, and more favorable tax rules.
Keep a close eye on how quickly these five newly appointed managers deploy their mandates over the coming quarters. If liquidity finally picks up in the local small- and mid-cap segments, Singapore's equity revival might finally match its reputation as a global wealth powerhouse.